

Only key users can manage triggers.
The built-in triggers
Each trigger below shows the administrations it applies to, and the conditions that raise an alert. An alert is only raised when all conditions are met. Most triggers look at the last closed financial year, and a few at the year-to-date figures.Weak liquidity (<1)
Weak liquidity (<1)
The company doesn’t have enough short-term means (cash, stock, unpaid invoices) to cover its short-term debts. This can be an early sign of payment trouble. Look at what’s actually tied up in those current assets (too much stock, too many unpaid invoices, or simply too little cash) and whether this is a longstanding issue or a recent change.Applies to: all administrationsRaises an alert when:
- Liquidity - Current ratio < 1 (last closed financial year)
Significant revenue decline in the last fiscal year
Significant revenue decline in the last fiscal year
In the past fiscal year, revenue has fallen by more than 5%. This may indicate loss of customers, a declining market, or a deliberate shift in focus. Check whether the decline is concentrated among certain customers or products, and whether it has been ongoing for several years.Applies to:
- Turnover > €25,000 (last closed financial year)
- Turnover growth ≤ −5% (last closed financial year)
Minimum company director remuneration
Minimum company director remuneration
The director’s wage is below the minimum threshold required to qualify for the reduced corporate tax rate (20% instead of 25% on the first bracket of profit). This may represent a missed tax optimization opportunity. Discuss with the client whether adjusting the remuneration (salary, director’s fee, or benefits) is feasible and worthwhile.Applies to:
- Company type is management company
- Legal type is BV or NV
- Directors’ remuneration < €50,000 (last closed financial year)
Low solvability (<25%)
Low solvability (<25%)
Less than 25% of total assets is financed with equity, indicating limited buffer to absorb losses and heavy reliance on lenders. When analysing, check the debt composition (short vs. long term), the multi-year trend, and solvability relative to sector peers.Applies to: all administrationsRaises an alert when:
- Solvability < 25% (last closed financial year)
Significant turnover decline in the current fiscal year (YTD)
Significant turnover decline in the current fiscal year (YTD)
The company has experienced a sharp decline in revenue from the start of the financial year until now compared to the same period last yearApplies to:
- Turnover ≥ €25,000 (last closed financial year)
- Turnover growth ≤ −5% (year to date)
Growth with financing pressure
Growth with financing pressure
Revenue is growing strongly, but that growth is burning cash: the need for working capital is increasing and the operating cash flow is negative. The company is currently financing its growth from reserves or short-term credit. This is normal with rapid growth, but it requires timely consultation about financing (credit line, factoring) before the leverage is exhausted.Applies to:
- Company type is operating company
- Turnover > €25,000 (last closed financial year)
- Turnover growth > 10% (last closed financial year)
- Working capital need > €0 (last closed financial year)
- Operational cash flow < €0 (last closed financial year)
Price pressure
Price pressure
The revenue has remained stable or increased, but the gross margin has dropped by more than 3 percentage points. This indicates more expensive purchasing, price pressure from customers, or a shift to a less profitable product or customer mix.Applies to:
- Turnover > €25,000 (last closed financial year)
- Company type is operating company
- Turnover growth ≥ 0% (last closed financial year)
- Change in gross margin as % of turnover ≤ −3 pp (last closed financial year)
Excess idle cash
Excess idle cash
There is more than 250,000 euros in cash in the account, combined with a high liquidity ratio. This capital probably yields little or nothing. This is a good time to discuss with the client: dividend distribution, reinvestment, or other ways to use the capital more efficiently.Applies to:
- Company type is operating company or management company
- Liquid assets ≥ €250,000 (year to date)
- Liquidity - Current ratio > 2 (year to date)
Indirect costs affect EBITDA margin
Indirect costs affect EBITDA margin
The turnover has remained stable or increased, as well as the gross margin, but the EBITDA margin has decreased by more than 5 percentage points. This means that indirect costs such as services and personnel weigh on the profitability of the organization.Applies to:
- Company type is operating company
- Turnover > €25,000 (last closed financial year)
- Change in gross margin as % of turnover > −1 pp (last closed financial year)
- Turnover growth ≥ 0% (last closed financial year)
- Change in EBITDA as % of turnover ≤ −5 pp (last closed financial year)
Negative equity
Negative equity
Equity is negative: accumulated losses exceed the capital contributed plus reserves. The company now has more liabilities than assets, which can trigger the statutory alarm-bell procedure. Look at how deeply negative, since when, and whether capital was recently injected or a further loss occurred.Applies to: all administrationsRaises an alert when:
- Equity < €0 (last closed financial year)
Operational loss
Operational loss
The company has revenue, but its core operations are losing money: operating costs exceed what’s coming in, before depreciation, interest, and tax are even factored in. This isn’t an accounting loss from one-off items — it points to a problem in day-to-day operations themselves. Look at which cost line is driving it (personnel, direct costs) and how long this has been going on.Applies to:
- Company type is operating company
- Turnover > €25,000 (last closed financial year)
- EBITDA ≤ €0 (last closed financial year)
Personnel cost growing faster than revenue
Personnel cost growing faster than revenue
Revenue held steady or grew, but personnel cost as a percentage of revenue increased by more than 3 percentage points. Wage costs are weighing more heavily than the revenue trend would explain — due to hiring, wage indexation, or declining productivity per employee. Check whether this is driven by headcount growth or a higher cost per employee.Applies to:
- Company type is operating company
- Turnover > €25,000 (last closed financial year)
- Turnover growth ≥ 0% (last closed financial year)
- Change in personnel costs as % of turnover > 3 pp (last closed financial year)
Conversion candidate: sole proprietorship to company
Conversion candidate: sole proprietorship to company
The profit is at a level where a company can be more tax advantageous than a sole proprietorship. This is an initial indication based on EBITDA. For a correct assessment, the actual taxable profit, social contributions, desired remuneration, and additional costs of a company must also be taken into account.Applies to:
- Legal type is natural person (sole proprietorship)
- EBITDA > €75,000 (last closed financial year)
Profit without cash generation
Profit without cash generation
The company is profitable on paper, but that profit isn’t turning into cash. The money is often tied up in unpaid invoices, stock, or slow customer payments. Check the trend in customer credit and stock levels to see where the cash is getting stuck.Applies to:
- Turnover > €25,000 (last closed financial year)
- Turnover > €0 (last closed financial year)
- EBITDA as % of turnover > 5% (last closed financial year)
- Operational cash flow ≤ €0 (last closed financial year)
Unsubscribe from a built-in trigger
If a built-in trigger isn’t useful for your firm, unsubscribe from it:- Click Triggers in the main rail.
- Click the three dots on the trigger’s tile, or at the top right when the trigger is open.
- Choose Unsubscribe from trigger.
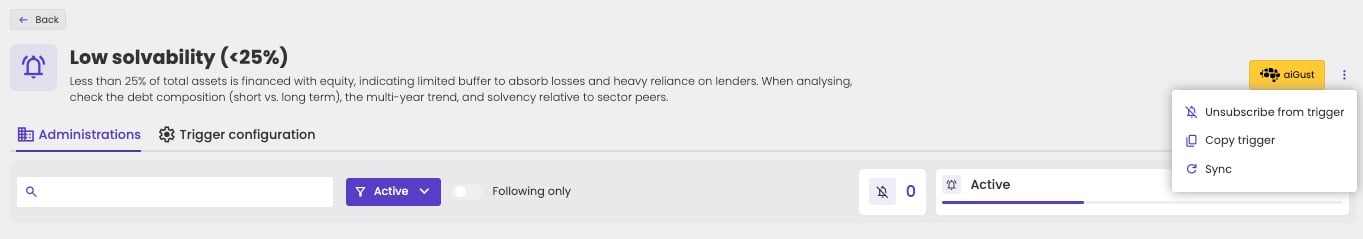
The menu of a built-in trigger.